
Case Study · D2C · Baby Care
The Moms Co, Malika Sadani’s toxin-free baby-care playbook
A mother who couldn’t find products she trusted for her own daughters built one of India’s best-known toxin-free mom-and-baby care brands, then sold it in the country’s largest D2C exit of 2021. A case study of positioning, content-to-commerce, and what happens to a brand after the founders cash out.
The thesis in one line
The Moms Co bet that Indian parents, especially new mothers, would pay a premium for personal-care products they could trust not to harm a baby, and that trust could be manufactured at scale through certification, dermatological testing and honest content rather than celebrity gloss. That single idea, held with discipline, turned a kitchen-table frustration into a brand that sold for a reported ₹500 crore in five years.
What follows is the how. How the positioning was chosen, how the brand acquired customers cheaply, where the money actually came from, and what the acquisition by the Good Glamm Group did to the story afterwards. The last part matters. A clean founding narrative and a headline exit are not the same as a durable outcome, and The Moms Co is a useful case precisely because the two diverged.
The founder: Malika Sadani
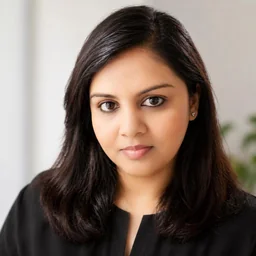
Malika Sadani (she has also been credited as Malika Datt Sadani) is the founder and CEO of The Moms Co. She built and ran the company with her husband and co-founder, Mohit Sadani. Malika owned the brand, product and community; Mohit ran operations and growth. This is worth stating plainly for the record: The Moms Co is a woman-founded, woman-led company, and Malika was the public face and chief executive throughout its independent life.
The origin story is not a marketing invention. Malika has said in interviews that after having children she went looking for safe personal-care products in India and kept hitting a wall. One of her daughters had sensitive skin, which sharpened the search. What she found on Indian shelves either carried ingredients she was uneasy about, or was imported, expensive and hard to get. The gap between what a cautious mother wanted and what the market offered became the company. She has framed the decision to start up around her daughters more than once, which is unusual candour for a founder narrative and became part of the brand’s own voice.
The couple set up the parent entity, Amishi Consumer Technologies Pvt Ltd, in 2016, and the brand went to market with its first products around early 2017. That two-step, incorporate in 2016 and launch in early 2017, is why you will see both years cited for the founding depending on whether a source counts the company or the first sale.
The problem and the insight
Baby care in India in the mid-2010s was dominated by a handful of legacy multinationals and a long tail of cheaper local products. The category ran on habit and trust built over decades. For a new brand, that looked like a wall. The insight was that the wall had a crack in it: a rising cohort of urban, digitally native, first-time parents who read ingredient labels, followed parenting content online, and no longer took a legacy brand’s safety for granted.
That shopper did not want cheaper. She wanted safer, and she wanted proof. The Moms Co built its whole proposition on supplying that proof. The tagline the brand became known for, “Nature In. Toxins Out.”, is a compressed version of the insight. It promised natural inputs and, just as important, the deliberate exclusion of a list of ingredients that anxious parents had learned to avoid. In a category where the buyer is buying peace of mind for someone who cannot speak for themselves, absence of harm sells as hard as presence of benefit.
Early days and the first products
The company started narrow. Rather than launch a sprawling catalogue, it built a focused range of mom-and-baby essentials: baby lotions, oils, washes and creams, alongside natural products for mothers, including during and after pregnancy. The early strategy was to own a small number of hero products, get the formulation and the safety story exactly right, and let repeat purchase and word of mouth do the rest.
Two decisions from this phase shaped everything after. First, the founders invested early in formulation and certification instead of treating them as afterthoughts, which meant the product could carry its safety claims honestly. Second, they treated the website and social channels as a place to teach, not just to sell. A worried parent researching “is this ingredient safe for a newborn” could land on The Moms Co content and come away informed. That behaviour, useful content pulling in exactly the customer you want, became the acquisition model. If you are building something similar, our guide on how to start an ecommerce business in India covers the plumbing underneath a launch like this.
The business model: how it makes money
At the simplest level, The Moms Co sells physical personal-care products at a gross margin and spends part of that margin acquiring and retaining customers. The interesting part is the shape of the machine.
The engine was content-to-commerce. Malika and Mohit have described building an audience of mothers first, understanding their questions and anxieties, and converting that audience into buyers whose trust had already been earned. Content and community lowered the cost of acquiring a customer, because the customer arrived warm. In a personal-care category where paid performance marketing on Facebook and Google was getting more expensive every year, a cheaper top-of-funnel was a real edge.
The revenue itself came from three surfaces. The brand’s own D2C website, where margins are highest and the customer relationship is owned. Online marketplaces, chiefly Amazon, Flipkart and beauty platforms such as Nykaa, where reach is large but the platform takes a cut. And offline retail, added later, to catch shoppers who still buy baby care in stores. By early 2022 the reported split was roughly 60 percent from marketplaces, about 20 percent from its own D2C site, and about 20 percent from offline retail. Read that carefully. Despite the “D2C brand” label, most of the money came through marketplaces, which is true of a great many Indian D2C names and matters for margins.
Go-to-market and distribution
The channel sequencing followed a logical order. Start on owned D2C to control the experience and gather first-party data. Expand onto marketplaces to reach the mass of shoppers who search on Amazon and Flipkart by default. Layer on beauty-specialist platforms where the shopper is already in a personal-care mindset. Add offline distribution once the brand had enough pull to justify shelf space. The table below sketches the reported channel mix around the time of the acquisition.
| Channel | Reported share (early 2022) | Role in the model |
|---|---|---|
| Online marketplaces (Amazon, Flipkart, Nykaa, etc.) | ~60% | Scale and reach; platform takes a commission |
| Owned D2C website | ~20% | Highest margin; owned customer data and relationship |
| Offline retail | ~20% | Catches in-store baby-care buyers; added later |
The lesson buried in that table is that “D2C” in India is often a brand-building label rather than a description of where sales happen. The Moms Co built the brand and the trust through direct channels and content, then monetised much of it through marketplaces. That is a sensible split, but it also means the brand carried marketplace economics, commissions, and heavy competition on the platform search page, on the bulk of its revenue.
Marketing and brand: trust as the product
The Moms Co’s marketing was unusually consistent for an early-stage brand. Every surface pointed back to safety and honesty. The brand name itself is a plain-spoken claim of belonging: this is the company for moms. The content was educational, aimed at the exact anxieties of a new parent, and the community of mothers gave the brand a feedback loop and a source of credibility that money cannot buy directly.
The certifications did heavy lifting here. Marketing that says “trust us” is weak. Marketing that says “here is the third-party certification, here is the dermatological testing, here is the list of what we leave out” is far stronger, because it externalises the trust to an independent authority. For founders thinking about how to build a brand voice that reads as human and credible rather than salesy, our note on personal branding for women entrepreneurs covers the same instinct applied to a person rather than a product.
The certification play
The Moms Co leaned hard on a specific credential. It marketed products as dermatologically tested and as Australia-certified toxin-free, referencing certification associated with Safe Cosmetics Australia and its Made Safe standard, alongside PETA cruelty-free certification. The choice of an Australian toxin-free benchmark was deliberate positioning. It signalled an external, first-world safety bar rather than a self-declared claim, which is exactly what a cautious buyer wants to see on a bottle going near a baby.
A fair note of caution belongs here. Third-party certification standards, their scope, and which specific SKUs carry which mark can change over time, and the meaning of any “toxin-free” label depends on the certifier’s own definition. This case study reports how the brand positioned itself and marketed those credentials. A shopper who needs the current certification status of a particular product should read the live label and the certifier’s published criteria rather than rely on a historical claim. What is not in doubt is the strategy: certification was the spine of the brand’s trust, not a footnote to it.
The funding journey
The Moms Co was venture-backed but not lavishly so by later-cycle standards. The founders started with their own money and a friends-and-family angel round, then brought in consumer-focused institutional investors who specialised in exactly this kind of brand. DSG Consumer Partners and Saama Capital were the recurring names across rounds, with venture debt from InnoVen Capital reported alongside the equity. Aggregate funding before the acquisition is generally put at around $15 million.
The exact labels and amounts wobble between trackers, which is normal for a private company whose rounds included extensions and bridges. Treat the table as a reported map, not audited accounts.
| Round / event | Reported timing | Reported amount | Lead / notable investors |
|---|---|---|---|
| Angel / friends & family | Around 2016 | ~₹1.15 crore | Founders, angels and early advisors |
| Series A | 2017 | ~$1 million | DSG Consumer Partners, Saama Capital |
| Series B (tranche) | 2019 | ~$3–5 million (reported) | DSG Consumer Partners, Saama Capital |
| Series B (further) | September 2020 | ~$8 million | DSG Consumer Partners, Saama Capital |
| Venture debt | Across the period | Not separately disclosed | InnoVen Capital |
| Acquisition (majority stake) | October 2021 | Deal reported ~₹500 crore | Good Glamm Group |
Two things stand out. The cap table stayed tight and strategic, dominated by consumer-brand specialists rather than generalist growth funds. And the total equity raised, around $15 million, was modest relative to the reported exit value, which is part of why the 2021 sale read as a strong outcome for the early backers. For founders weighing how much outside money to take, our explainer on a business loan for women in India is a reminder that equity is not the only fuel.
Financials and scale, hedged
The Moms Co grew revenue steadily while running losses, which was the standard shape of a scaling Indian D2C brand in this era. Based on filings summarised by the business press, operating revenue was roughly ₹52.5 crore in FY22 and about ₹73.5 crore in FY23, growth of around 40 percent. Over the same FY23 period the net loss reportedly widened to about ₹64 crore, up sharply year on year. The brand was buying growth, and the growth was real, but it was not yet paying for itself.
After the acquisition, reading The Moms Co’s standalone economics gets harder. Once a brand sits inside a larger house of brands, costs and revenues get shared and reallocated, and the parent’s consolidated numbers dominate the public reporting. So the honest position is this: the pre-acquisition trajectory is reasonably well documented and points to a fast-growing, loss-making brand; the post-acquisition standalone performance is not cleanly in the public record, and we will not invent it.
The turning point: the Good Glamm acquisition
In October 2021 the Good Glamm Group acquired a majority stake in The Moms Co in a deal widely reported at around ₹500 crore, described at the time as one of the largest Indian D2C exits of the year. The structure was reported as cash and stock. Early institutional investors including DSG and Saama took a full exit, while the founders took a partial one and stayed involved, with The Moms Co becoming the mother-and-baby pillar of Good Glamm’s emerging portfolio.
For Malika and Mohit this was a rational outcome. A brand raised on roughly $15 million changing hands at a reported ₹500 crore is a genuine success by the numbers, and it delivered liquidity to backers who had been in since the early rounds. It is the kind of result that makes the earlier discipline, the tight cap table and the cheap content-led acquisition, look vindicated. The exit is the part of the story most retellings stop at.
Inside Good Glamm’s house-of-brands bet, and the turbulence
The Good Glamm Group was building a “house of brands”, buying up digital-first beauty and personal-care labels and stitching them together with shared content, marketing and distribution. The Moms Co was one of its larger and more prized acquisitions, sitting alongside names such as St.Botanica, Organic Harvest and the feminine-hygiene brand Sirona. On paper, a mother-and-baby brand with strong trust equity slotted neatly into a portfolio aimed at women across life stages. Good Glamm reportedly kept increasing its stake in The Moms Co over the following years, and by late 2024 press reports described a completed 100 percent buyout of the founders’ remaining shares.
The wider bet did not age well. Through 2024 and into 2025, the Good Glamm Group ran into a serious cash and funding crunch. Indian business press reported delayed salaries stretching across months, multiple rounds of layoffs, and a scramble to raise money, with the CEO Darpan Sanghvi publicly acknowledging the crisis and tracing part of it to a funding-cycle squeeze and a late-stage deal that fell through. The group reportedly put several brands, including The Moms Co, Organic Harvest and Sirona, up for sale to stay afloat, and Sirona was reported to have been sold back to its original founders at a fraction of what Good Glamm had paid for it.
For a case study, this is the most instructive turn. The acquisition that looked like a clean win for The Moms Co’s founders in 2021 handed the brand’s day-to-day fate to a parent whose roll-up model came under real strain. The brand’s underlying franchise, trusted toxin-free mom-and-baby care, is separable from the parent’s troubles, and the specifics of any onward sale of The Moms Co should be checked against the latest reporting rather than assumed. But the structural lesson stands. When you sell into a house of brands, you are also buying exposure to that house’s balance sheet.
Competition
The Moms Co never had the field to itself. On one side sat the legacy multinationals with decades of trust, deep pockets and shelf dominance in baby care. On the other, a wave of new-age natural and toxin-free brands crowded the same insight the company had spotted, most visibly Mamaearth, which grew faster, raised far more, and eventually went public. Mamaearth’s scale is the clearest evidence that the toxin-free positioning was a large opportunity, and also the clearest reason The Moms Co found it hard to win the category outright as an independent.
That competitive reality is part of the acquisition logic. Against a much larger, better-capitalised rival chasing the same shopper, joining a house of brands with shared marketing muscle was a defensible move rather than a defeat. The category was real; owning it alone, on modest capital, was the hard part.
Challenges and criticism
Covered neutrally, the brand’s difficulties are the ordinary ones of scaling D2C plus the specific ones of its exit. Revenue grew but losses grew faster, which is a fragile pattern once cheap capital dries up. Most revenue came through marketplaces, so the brand carried platform commissions and intense on-platform competition on the bulk of its sales, which pressures margins. The toxin-free and natural personal-care space became crowded and noisy, and safety claims across the whole category have drawn scrutiny, which raises the bar for any single brand’s marketing to stay precise and defensible.
The sharpest lesson, though, is post-exit. A founder can run a clean, well-positioned company and still watch the brand land inside a troubled parent. None of the Good Glamm turbulence reflects a failure of The Moms Co’s original product or positioning. It reflects the reality that an exit transfers control, and control includes the downside.
What founders can learn from The Moms Co
1. Sell trust, and then prove it
In categories where the buyer is anxious, baby care, health, food for children, the winning proposition is often the absence of harm rather than a novel benefit. The Moms Co built its whole brand on trust and then externalised that trust with certification and dermatological testing. Claims are cheap; proof is defensible. Decide early which of your promises you can hand to an independent authority to verify.
2. Content and community can be your cheapest channel
The content-to-commerce engine let the brand acquire warm customers as paid marketing kept getting more expensive. This only works when the content is genuinely useful to the exact person you want to sell to. If your content would embarrass you as a customer, it will not lower your acquisition cost. If it would genuinely help a worried parent at 2am, it will. Our field notes on Instagram marketing for small business get into the mechanics of doing this without a big budget.
3. Know where your money actually comes from
“D2C brand” is a story; the channel mix is the truth. Most of The Moms Co’s revenue came through marketplaces, not its own site. That is fine, but it means your margins, your competition and your customer data all look different from the D2C fantasy. Model your business on where the sales really land, not on the label you use in your pitch deck.
4. An exit is a transfer of control, so price the downside
The 2021 sale was a strong result. It was also the moment the brand’s fate moved onto someone else’s balance sheet. Good Glamm’s later crisis had nothing to do with The Moms Co’s product and everything to do with the acquirer. When you sell, you are marrying your brand to the buyer’s financial health. Diligence on the acquirer is as important as the headline number, especially in a cash-and-stock deal where part of your payout rides on the parent’s future.
Timeline of key milestones
| Year | Milestone (as reported) |
|---|---|
| 2016 | Amishi Consumer Technologies incorporated by Malika and Mohit Sadani; angel round of about ₹1.15 crore |
| Early 2017 | The Moms Co brand launches with toxin-free mom-and-baby products |
| 2017 | ~$1 million Series A led by DSG Consumer Partners and Saama Capital |
| 2019 | Series B tranche from existing investors; catalogue and channels expand |
| September 2020 | ~$8 million round reported for product expansion and tech |
| October 2021 | Good Glamm Group acquires a majority stake; deal reported ~₹500 crore; early investors exit |
| 2022–2023 | Operates inside Good Glamm; revenue ~₹73.5 crore in FY23 with a widened net loss |
| 2023–2024 | Good Glamm raises its stake; reports of a completed 100% buyout of founders by late 2024 |
| 2024–2025 | Good Glamm hits a cash crunch, salary delays and layoffs; brands including The Moms Co reportedly put up for sale |
What we don’t know
Several things sit outside the verified public record and we have not guessed at them. Exact round labels and amounts vary between trackers, so the funding table is a reported map rather than audited history. The Moms Co’s standalone financials after the acquisition are not cleanly separable from Good Glamm’s consolidated numbers. The precise, current status of any onward sale of The Moms Co, and its ownership at the moment you are reading this, should be checked against the latest reporting, since the parent’s restructuring was still moving. And the live certification status of any individual product should be read off the current label, not inferred from historical marketing. Where we could not stand behind a number, we said so.
Sources & further reading
Primary and reference sources used in this case study:
- The Moms Co, the brand’s own site and product materials: themomsco.com
- Good Glamm Group, the parent house of brands: goodglammgroup.com
- Saama Capital, an early lead investor: saama.vc
- DSG Consumer Partners, an early lead investor: dsgcp.com
Press and data coverage referenced (in alphabetical order): Business Standard, Crunchbase, Dealroom, The Economic Times, Entrackr, Inc42, Mint, Outlook Business, SME Futures, Storyboard18, Tracxn, YourStory. Funding and financial reporting is most concentrated on Inc42, Entrackr, Tracxn and YourStory; the Good Glamm crisis reporting is most concentrated on Inc42, Outlook Business, Storyboard18 and YourStory; founder interviews are most concentrated on YourStory and SME Futures.
If you spot a factual error in this case study, please write to [email protected] and we’ll correct it with an editor’s note.
Related reading on Women Can Startup
- Nykaa case study
- Mamaearth case study
- SUGAR Cosmetics case study
- MobiKwik case study
- Biocon case study
- Zivame case study
- LimeRoad case study
- SHEROES case study
- Menstrupedia case study
- All Women Can Startup case studies
- Women founder stories
- How to write a business plan
- Business loans for women in India
- How to get media coverage for your startup
- Personal branding for women entrepreneurs
- How to start an ecommerce business in India
- Instagram marketing for small business
Sources and further reading
- The Moms Co, official brand website
- Malika Datt Sadani, founder & CEO, verified LinkedIn profile
- The Moms Co, Crunchbase company & funding profile
- The Moms Co, Tracxn company profile, funding & financials
- YourStory: The Moms Co raises $1M Series A led by Saama Capital and DSG Consumer Partners
- Inc42: The Moms Co raises $8M Series B for product expansion
- SME Futures interview: ‘I became an entrepreneur because of my daughters’, Malika Sadani
- YourStory: The Good Glamm Group acquires 100% stake in The Moms Co
- Inc42: The fall of Good Glamm Group, how the house of brands crumbled
- Outlook Business: What triggered the Good Glamm Group’s collapse, CEO Darpan Sanghvi opens up
More for founders
- Women-led startup directorySearch 100+ women-led Indian companies by industry, city, funding stage and year.
- VC directoryWhich funds invest in India, at what stage and cheque size, and who they’ve backed.
- Startup trends & dataLive charts of women-led startups in India — sectors, funding stages and cities.
- Free founder toolkit100+ directories, grants, PR, templates, AI tools and India’s schemes.
- Funding MatchFind the government funding you actually qualify for — in 60 seconds.
- Templates & checklistsPitch deck, cap table, term sheet and founders’ agreement.
Comments
No comments yet — be the first to add one.